STORY
Mom Kicked Me Out For Living “Rent-Free”—Until The Next Mortgage Payment Bounced
‘Put Mom on speaker,’ I said into the phone, my voice echoing softly against the bare walls of my fourth-floor studio apartment.
Three hundred yards outside my window, commuter traffic hummed along the wet avenue, ordinary and unbothered. Inside my apartment, I had a folding chair, a twin mattress in the corner, two unpacked cardboard boxes, and my thick blue plastic folder spread open across the laminate countertop. Yet for the first time in nearly three years, my chest felt completely uncrushed.
On the other end of the line, I heard the fumble of a phone being taken off a sweat-slicked ear, followed by the hollow tap of my father’s thumb hitting the speaker icon.
‘Claire?’ my mother’s voice rang out, sharp and brittle, pitched half an octave higher than the cold, regal tone she had used four weeks ago when she pointed me toward the front door like a stray dog. ‘Claire, listen to me right now. Stop being petty and log back into the portal! Tell Mr. Vance that the returned draft was a bank error and that you signed the August modification!’
I didn’t raise my voice. I didn’t have to.
‘Which document in the August packet, Mom?’ I asked clearly enough for the microphone to catch every consonant. ‘The $185,000 home-equity line of credit where you forged my signature using the W-2s you took out of my desk drawer? Or the $52,000 disbursement check four days later that paid off Ethan’s sportsbook debt and put him in a lifted pickup truck?’
For three heartbeats, nobody breathed on Oak Hollow Lane. Even the wind in their front-porch trees seemed to go still.
Then a calm, measured male voice spoke up from the background on their porch. ‘Mrs. Cole, please step back from the telephone. Ms. Claire Cole, this is Arthur Vance with First Heritage Bank’s Special Investigations and Title Compliance Unit. Are you able to drive to the property right now, or would you prefer to meet me at the county branch with our notary?’
‘I’m already putting my coat on, Mr. Vance,’ I said. ‘I have the original blue folder in my hand. I’ll be in the driveway in fifteen minutes.’
I hung up before my mother could scream my name again.
As I walked down the stairwell to my ten-year-old Honda Civic—the same car Ethan used to take without asking while telling me to relax—my mind flashed back to how blind I had allowed myself to be in the name of family loyalty.
Four weeks earlier, on that Sunday afternoon in my parents’ kitchen, I had genuinely believed my only problem was ingratitude. For thirty-four consecutive months, ever since my father claimed his machine-shop hours had been cut and my mother swore they were just ‘ninety days behind after a bad tax year,’ I had carried that house on my back. It started with covering the electric bill when a pink shutoff notice arrived on the hall table. Two weeks later, it was the water bill. The month after that, my mother sat at the kitchen island with red eyes and a trembling lower lip, asking if I could link my checking account to the First Heritage mortgage portal ‘just until the autumn overtime kicks in.’
Autumn turned into winter. Winter turned into three years.
Every single month, $2,840 vanished from my checking account on the first business day. Meanwhile, my twenty-six-year-old brother Ethan quit one job because his supervisor ‘disrespected his schedule,’ quit another because the commute was twenty-five minutes too long, and spent his afternoons sleeping until one o’clock before raiding the groceries I bought on my way home from my accounting firm. Whenever I brought up the bills, my mother acted as though I were holding a knife to their throats. Whenever Ethan took my car and brought it back on fumes, I was told I was ‘creating drama.’
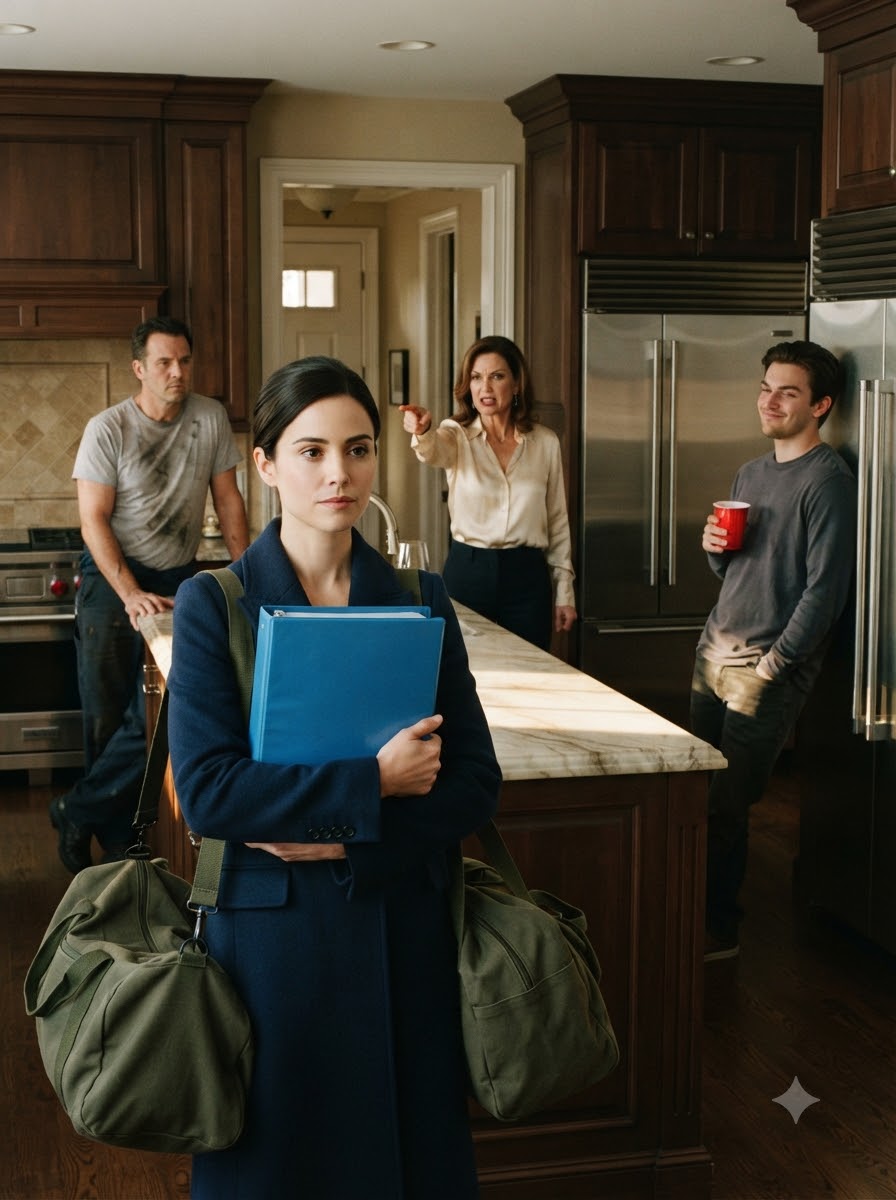
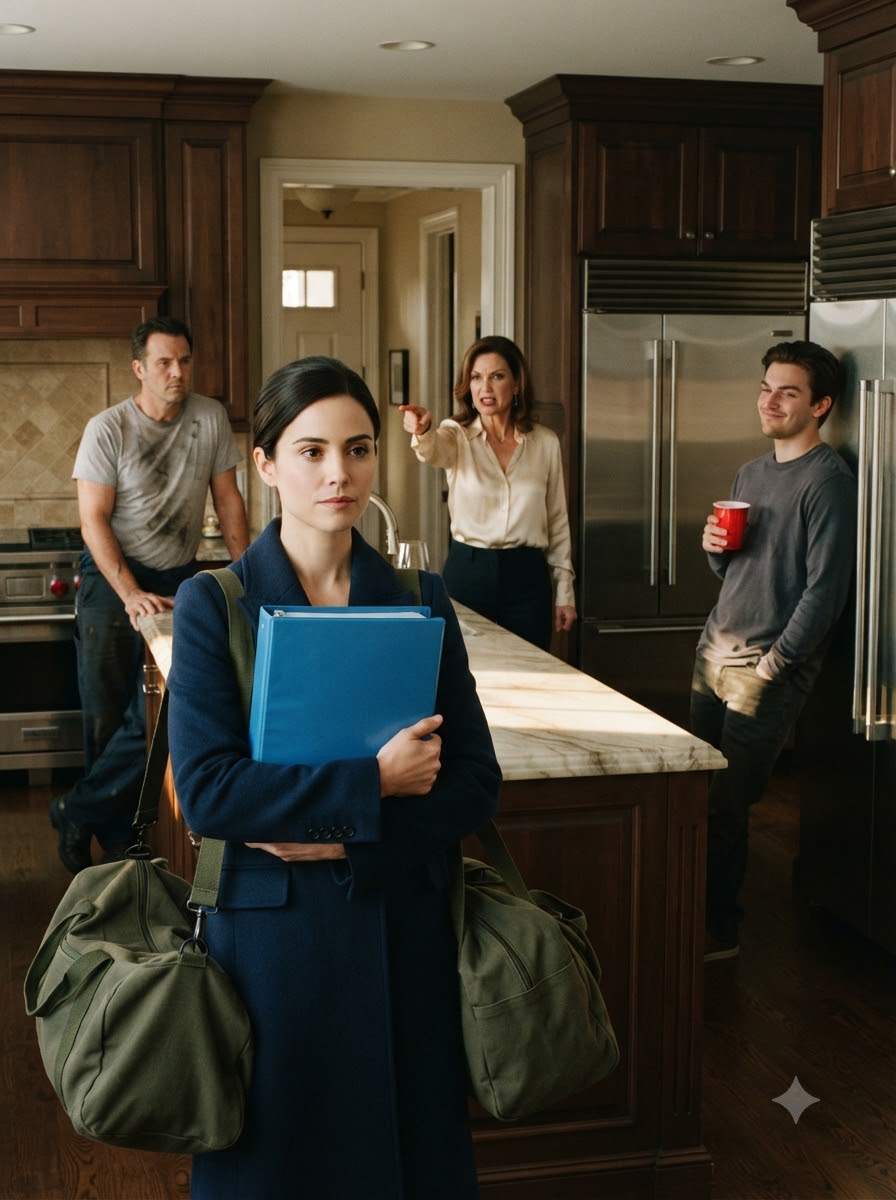
So when my mother laughed in my face that Sunday afternoon, claimed I lived there rent-free, and told me to get out and never come back while my father leaned against the counter with grease on his hands and Ethan smirked into his gas-station soda, the thread holding my guilt together finally snapped.
What they didn’t know was what happened two hours after I drove away.
That night, parked under the buzzing amber floodlight of a roadside motel three miles off the highway, I opened my laptop to sever my bank account from their lives. When I logged into the First Heritage online portal to delete my checking routing number, a red banner popped up across the screen:
WARNING: Removing Primary Auto-Debit Account #4409 violates the Rate-Lock & Occupancy Covenant of Secondary Loan #HELOC-8841-COLE. Manual verification by Co-Borrower Claire E. Cole will be required prior to the next billing cycle.
I stared at the screen until the letters blurred.
Secondary Loan #HELOC-8841-COLE.
With shaking fingers, I unzipped the blue plastic folder I had packed from my bedroom desk and pulled out the homeowner’s insurance renewal binder I had paid the previous month. At the time, my mother had handed me only the payment stub over breakfast, claiming the bank account was short and the policy would lapse at midnight if I didn’t put the $1,900 charge on my debit card. Three days after I paid it, the insurance company had automatically emailed a PDF of the full declaration packet to the email address attached to the card—mine. Because I had been buried in quarter-end audits at work, I had printed the confirmation page, shoved it into my folder, and never scrolled down to Page 4 of the PDF.
Sitting in that motel parking lot, I opened the full email attachment.
There, under ‘Additional Listed Mortgagees and Lienholders,’ right below the original 2014 mortgage that only had $94,000 left on the principal, was a second recorded deed of trust dated August 14th of that year for $185,000.
And listed as Primary Income Co-Borrower and Personal Guarantor was my full legal name: Claire Evelyn Cole.
I clicked into the ‘Recorded Documents’ tab on the First Heritage portal. Because my login credentials were tied to the checking account funding the payments, the system displayed the entire scanned underwriting packet from August. For twenty minutes in that silent car, with rain beginning to streak the windshield, I read every page.
Eight months earlier, my parents had applied to pull nearly all the equity out of the house. On their own, they had been rejected instantly—my father’s credit score was in the low five-hundreds after two repossessions, and my mother hadn’t worked a full-time job in twelve years. The loan officer’s notes were right there in the file: Household income insufficient unless adult resident daughter Claire E. Cole (whose checking account #4409 has satisfied 26 consecutive monthly drafts) co-signs as primary income earner.
Two days after that note was entered, someone uploaded my last two years of W-2s, four of my paystubs—which I kept in the top drawer of my bedroom desk—and a notarized Co-Borrower Signature Addendum.
The signature on the line was a careful, looping imitation of mine. The capital ‘C’ had the exact slight hook my mother always used when signing birthday cards. And the notary stamp belonged to a man named Marcus Bell—the finance manager at the used-car lot where Ethan’s best friend worked.

More From This Author